WhatsApp us on +91 9091913999 or Call us on +91 9811881981
LEGAL INSIGHT 007 | 07 OCTOBER 2026 PrivatBank and Kolomoisky Win Investment Arbitration Awards Against Russia Over Crimea Expropriation
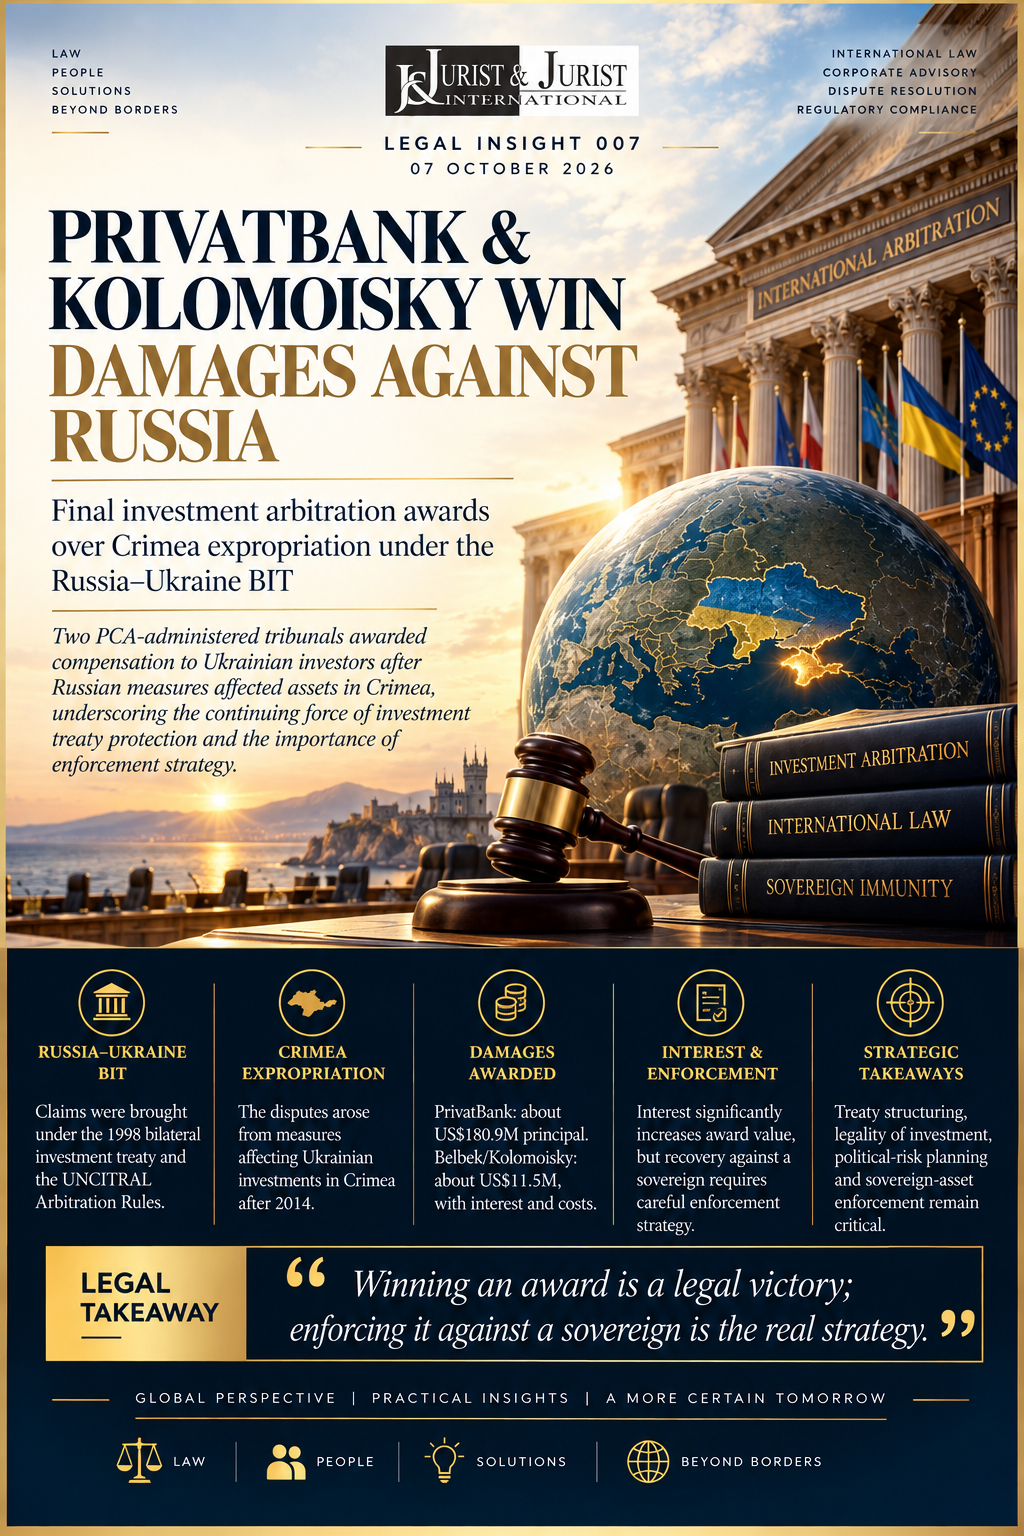
Two final investment arbitration awards against the Russian Federation have brought renewed focus to the protection of foreign investments during territorial and political upheaval, the application of bilateral investment treaties, and the challenges of enforcing arbitral awards against sovereign States.
On 1 October 2026, arbitral tribunals in JSC CB PrivatBank v. The Russian Federation and Aeroport Belbek LLC and Mr. Igor Valerievich Kolomoisky v. The Russian Federation issued final awards concerning Ukrainian investments affected following Russia’s assumption of control over Crimea.
The Permanent Court of Arbitration (PCA), which provided administrative support in both proceedings, announced the final awards on 6 October 2026. Both cases were investment arbitrations conducted under the UNCITRAL Arbitration Rules 1976 pursuant to the 1998 Russia-Ukraine Bilateral Investment Treaty (BIT).
The disputes are important not merely because compensation has now been awarded. They address a difficult question at the intersection of international investment law, territorial control and sovereign responsibility:
Can an investment originally situated within the investor’s own State become protected as a foreign investment when another State subsequently assumes control over the territory in which that investment is located?
The Crimean investment arbitrations demonstrate how investment treaty protections may operate even in highly unusual circumstances where geopolitical events fundamentally alter the legal and factual environment surrounding an investment.
THE DISPUTES: UKRAINIAN INVESTMENTS IN CRIMEA
PrivatBank, a Ukrainian financial institution, had carried on banking operations and maintained assets in Crimea before the events of 2014.
The separate Belbek arbitration involved Aeroport Belbek LLC and Igor Kolomoisky, whose investment concerned rights associated with the commercial passenger terminal at Belbek Airport near Sevastopol, including investments made in the development and operation of the terminal.
Following Russia’s assumption of control over Crimea, the investors alleged that actions attributable to the Russian Federation deprived them of their businesses, property and economic interests.
The claims were consequently pursued under the Agreement between the Government of the Russian Federation and the Cabinet of Ministers of Ukraine on the Encouragement and Mutual Protection of Investments dated 27 November 1998.
The PrivatBank arbitration, PCA Case No. 2015-21, was brought under that bilateral investment treaty and conducted under the UNCITRAL Arbitration Rules 1976.
THE CENTRAL JURISDICTIONAL ISSUE: WHEN TERRITORY CHANGES, WHAT HAPPENS TO THE INVESTMENT?
The unusual feature of the Crimea-related investment arbitrations was that the investments were originally made by Ukrainian investors in territory recognised internationally as part of Ukraine.
Ordinarily, bilateral investment treaties protect investments made by nationals of one contracting State in the territory of the other contracting State. At the time the original investments were made, therefore, they were not conventional Ukrainian investments made in Russian territory.
The circumstances changed dramatically after Russia assumed effective control over Crimea in 2014. The tribunals were required to consider whether the protections of the Russia-Ukraine BIT became applicable to Ukrainian investments situated in territory subsequently controlled by Russia.
This jurisdictional question became one of the defining legal issues in the Crimea investment arbitration cases. The significance extends beyond the immediate Russia-Ukraine dispute.
LIABILITY FOR EXPROPRIATION HAD ALREADY BEEN DETERMINED
The October 2026 final awards are the culmination of proceedings that began more than a decade ago.
In the Belbek arbitration, the tribunal issued an Interim Award on 24 February 2017 concerning jurisdiction and admissibility. A Partial Award dated 4 February 2019 subsequently addressed liability and remaining jurisdictional and admissibility issues, while the question of compensation continued into a separate quantum phase.
The PrivatBank proceedings similarly progressed through jurisdiction, liability and quantum stages before reaching the final award. By the time of the October 2026 decisions, the principal question was no longer simply whether treaty obligations had been breached, but how the investors’ losses should be valued and compensated.
Investment arbitration frequently proceeds in separate stages: Jurisdiction -> Liability -> Quantum -> Enforcement. A claimant may therefore establish a treaty breach years before receiving a final determination of the monetary compensation due.
THE PRIVATBANK AWARD
In JSC CB PrivatBank v. The Russian Federation, the tribunal issued its final award following years of proceedings relating to the loss of PrivatBank’s banking assets and operations in Crimea.
The case also involved an objection by Russia concerning the alleged illegality of aspects of PrivatBank’s investment. The later phase of the arbitration concerned both quantum and Russia’s illegality objection, including evidence and submissions concerning Russian law and valuation.
According to reporting concerning the final award, PrivatBank received approximately US$180.9 million in principal compensation, together with substantial interest and applicable costs.
Because interest runs from events dating back to 2014, the overall economic value reported in connection with the award is significantly higher than the principal damages figure. In long-running international arbitration, pre-award and post-award interest can materially change the value of an arbitral award, particularly where the underlying deprivation occurred many years before the final determination of damages.
THE BELBEK AND KOLOMOISKY AWARD
The second arbitration concerned Aeroport Belbek LLC and Igor Valerievich Kolomoisky and their investment in the commercial passenger terminal at Belbek Airport.
The proceedings were registered as PCA Case No. 2015-07 and arose under the same 1998 Russia-Ukraine BIT.
The tribunal ultimately awarded approximately US$11.5 million, together with interest and applicable costs. Although materially smaller than the PrivatBank award, the Belbek decision is legally significant because it forms part of the wider body of investment arbitration arising from the treatment of Ukrainian-owned assets in Crimea.
WHY THE PRIVATBANK AND KOLOMOISKY AWARDS MATTER FOR INTERNATIONAL INVESTMENT LAW
The two awards carry implications beyond Crimea. They provide useful guidance for investors, multinational companies and governments dealing with investments exposed to political instability, territorial disputes or sovereign intervention.
- Investment Treaty Protection Can Become Relevant After a Change in Territorial Control
The most distinctive aspect of these cases is that the investments were not originally structured as conventional foreign investments in Russia. The change in governmental control over Crimea subsequently created the basis upon which treaty protections were invoked.
For international investors, the lesson is that political events can fundamentally alter the treaty character and legal exposure of an investment. Territorial change, occupation, annexation or other shifts in sovereign control may therefore raise investment treaty questions that did not exist when the original investment was made.
- Expropriation Is Not Limited to Formal Nationalisation
International investment law does not treat expropriation solely as a situation in which a government formally transfers legal title to itself.
Depending upon the wording of the applicable treaty, expropriation may also arise where State measures effectively deprive an investor of control over its investment, the ability to operate the business, use of underlying assets, economic benefits associated with the investment, or the substantial value of the investment.
The Crimean cases illustrate why companies operating in politically sensitive jurisdictions must consider effective loss of control and economic deprivation, not merely formal ownership.
- Jurisdiction Can Determine the Entire Investment Arbitration
The merits of an investor’s grievance may be commercially compelling, but an arbitral tribunal cannot decide the substance of a claim unless jurisdiction is first established.
Investment arbitration therefore frequently turns on preliminary questions concerning the nationality of the investor, the existence of a qualifying investment, the territory in which the investment is situated, treaty interpretation, the date on which treaty obligations became applicable, the legality of the investment, and the scope of the State’s consent to arbitration.
The PrivatBank and Belbek disputes demonstrate that these issues can themselves involve years of litigation before damages are finally determined.
THE LEGALITY OF THE INVESTMENT REMAINS A CRITICAL ISSUE
The PrivatBank proceedings also highlight the growing significance of legality objections in investor-State arbitration.
States increasingly argue that investors should not receive treaty protection where the relevant investment was allegedly obtained, structured or operated contrary to applicable law. Depending upon the wording of the investment treaty and the nature of the alleged illegality, such an objection can potentially affect jurisdiction, admissibility or the merits of the claim.
For investors, this creates an important compliance lesson. Investment protection cannot be considered independently from anti-corruption compliance, corporate governance, licensing requirements, ownership documentation, regulatory approvals and lawful acquisition of the underlying investment.
A properly documented and legally compliant investment structure can become critical evidence years later if a treaty dispute arises.
INVESTMENT STRUCTURING SHOULD BEGIN BEFORE CAPITAL IS DEPLOYED
One of the strongest commercial lessons arising from international investment arbitration is that treaty protection should be considered before, rather than after, a dispute begins.
Companies entering foreign markets should assess not only commercial returns and regulatory requirements, but also the legal architecture protecting the investment. This can include applicable bilateral investment treaties, investment chapters contained in trade agreements, nationality of the investing entity, intermediate holding structures, protection against expropriation, fair and equitable treatment obligations, transfer-of-funds protections, access to investor-State arbitration, and jurisdictions where an eventual award could realistically be enforced.
Investment treaty planning should therefore form part of cross-border transaction structuring and political-risk management. It should not begin only after government action has already affected the investment.
AN ARBITRAL AWARD IS NOT THE SAME AS RECOVERY
The final awards represent important legal victories for the investors. However, obtaining an investment arbitration award against a sovereign State does not necessarily result in immediate payment.
Where the respondent State does not voluntarily comply with an award, the investor may need to undertake a separate international enforcement strategy. That process can involve identifying jurisdictions in which the respondent State possesses assets and determining whether those assets can lawfully be attached.
The analysis may include recognition and enforcement of the arbitral award, the law of the jurisdiction where enforcement is sought, sovereign immunity from jurisdiction, immunity from execution, distinction between sovereign and commercial State assets, sanctions and regulatory restrictions, challenges to the arbitral award, and tracing of assets potentially available for execution.
The Belbek arbitration has already generated related proceedings before Dutch courts, including proceedings before the Hague Court of Appeal in 2026 concerning Russia’s efforts to challenge earlier arbitral and judicial decisions. The next chapter may therefore be determined as much by international enforcement law and sovereign immunity as by investment treaty law itself.
A BROADER LESSON FOR CROSS-BORDER INVESTORS
The PrivatBank and Kolomoisky awards illustrate the continuing relevance of international investment treaties as instruments for managing sovereign and political risk.
Foreign investors increasingly operate in jurisdictions where commercial risk may become intertwined with geopolitical instability, sanctions, territorial disputes, regulatory intervention, national security measures, State seizure of assets and major changes in governmental policy.
In those circumstances, contractual protection alone may not always be sufficient. A commercial contract establishes rights against the contractual counterparty. An investment treaty, where applicable, can potentially create separate international law protections against the host State itself.
That distinction is one of the fundamental reasons why investment treaty structuring has become an important component of sophisticated international transactions.
LEGAL TAKEAWAY
The PrivatBank v. Russia and Aeroport Belbek and Kolomoisky v. Russia awards demonstrate that investment treaty protection can assume particular importance when extraordinary political or territorial changes substantially interfere with private investments.
First, treaty protection should be considered at the investment-planning stage. International businesses should understand which bilateral investment treaties and investment agreements may protect their capital before entering a foreign jurisdiction.
Second, expropriation is wider than formal confiscation. A State measure that substantially deprives an
investor of the control, operation or economic value of an investment may potentially engage international investment protections depending upon the applicable treaty.
Third, winning an arbitration is only one stage of the recovery strategy. Where a sovereign State does not voluntarily satisfy an award, recognition, sovereign immunity, asset identification and enforcement may become as important as the original arbitration.
For businesses investing across borders, the larger lesson is clear: International investment protection should be treated as part of transaction planning, political-risk management and dispute strategy from the beginning – not merely as a remedy considered after an investment has already been lost.
SOURCE
- Global Arbitration Review (GAR), ‘PrivatBank and Kolomoisky win damages against Russia’, 6 October 2026.
- Permanent Court of Arbitration, JSC CB PrivatBank v. The Russian Federation, PCA Case No. 2015-21, Final Award dated 1 October 2026 / announced 6 October 2026.
- Permanent Court of Arbitration, Aeroport Belbek LLC and Mr. Igor Valerievich Kolomoisky v. The Russian Federation, PCA Case No. 2015-07, Final Award dated 1 October 2026 / announced 6 October 2026.
- Proceedings under the 1998 Agreement between the Government of the Russian Federation and the Cabinet of Ministers of Ukraine on the Encouragement and Mutual Protection of Investments, conducted under the UNCITRAL Arbitration Rules 1976.
Copyright © 2012-2025. Jurist & Jurist International is a registered trademark. Unauthorized use, reproduction, or imitation of our name, logo, or design is strictly prohibited and punishable under applicable laws.
Designed by RICKYTECH & CO.